Confirmation Statement: Filing, Deadlines and Late Penalties
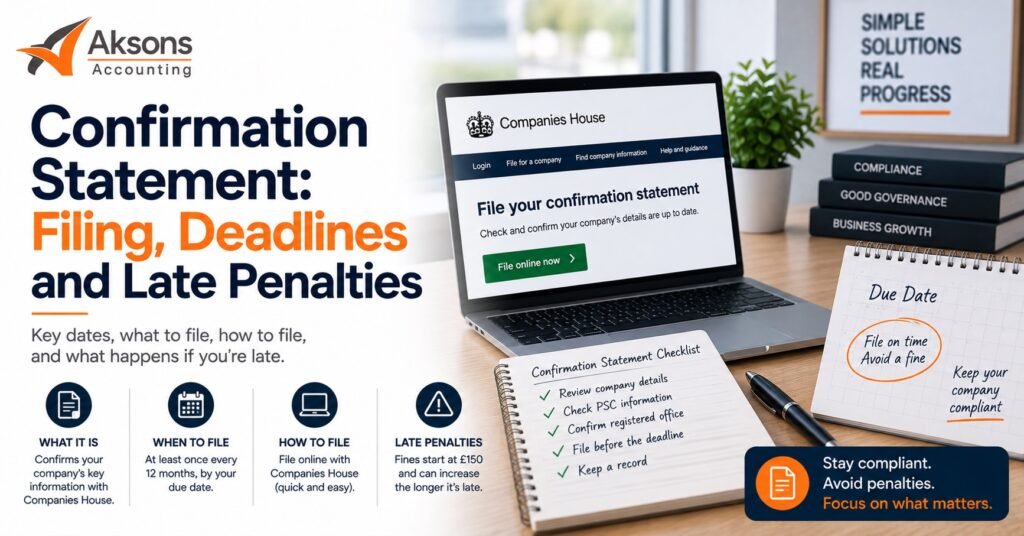
Quick Summary: The confirmation statement is the simplest filing a limited company makes and the one most likely to end in a company being struck off, because there is no automatic fine to prompt anyone into action. This guide covers what actually determines whether yours goes through cleanly: how to find your real deadline from your review period rather than guessing at an anniversary, which details must be changed on separate forms before you file rather than on the statement itself, the step-by-step filing process including the identity verification requirement that now sits in front of it, what late filing genuinely costs when there is no penalty scale, and how to stop a strike-off once a Gazette notice has been published
Why This Filing Catches Out Directors Who Are Otherwise Organised
Late annual accounts generate an automatic penalty. £150 the moment you are a day late, rising to £1,500 at six months. The letter arrives, the money is demanded, and the problem gets dealt with.
The confirmation statement works differently. There is no automatic fixed penalty for filing it late. Nothing arrives demanding money. For a director watching deadlines by which ones cost them, it registers as the least urgent thing on the list.
That is exactly why it is dangerous. What the confirmation statement carries instead of a fine is the risk of the company being removed from the register altogether. Missing it is a criminal offence for the directors, the overdue status appears publicly on your company’s page for anyone running a credit check, and persistent failure leads to compulsory strike-off, dissolution, and the company’s assets passing to the Crown.
The absence of a penalty is not leniency. It is the reason directors do not act until the Gazette notice arrives, and by then the situation is considerably harder to fix.
What the Confirmation Statement Actually Is
It is an annual check that the information Companies House holds about your company is still correct. It replaced the old annual return in June 2016, and the change was substantive: the annual return required you to re-enter everything, while the confirmation statement asks you to confirm the existing record and flag what has changed.
| | Confirmation statement (CS01) | Annual accounts |
| What it contains | Company details on the public register | Financial position and performance |
| Filed with | Companies House | Companies House and HMRC |
| Deadline based on | Review period | Accounting reference date |
| Late penalty | None automatic, but strike-off risk | £150 to £1,500 automatic |
| Required if dormant | Yes | Yes |
It contains no financial information at all. No turnover, no profit, no tax. Directors who assume their accountant “does the Companies House filing” sometimes mean the accounts and nothing else, which is how a statement goes unfiled for a year without anyone noticing.
Every company registered at Companies House must file one, including dormant companies, non-trading companies and companies that have never issued an invoice. The legal responsibility sits with the directors, not with whoever files on their behalf.
Finding Your Deadline: The Review Period
Section 853A of the Companies Act 2006 sets the timetable, and it works on review periods rather than fixed anniversaries.
- Your first review period starts on the date of incorporation and runs for 12 months.
- Each subsequent review period begins the day after the previous one ended and runs for 12 months.
- You have 14 days after the review period ends to file.
Working example. Your company was incorporated on 15 March 2025.
| Stage | Date |
| First review period | 15 March 2025 to 14 March 2026 |
| Filing deadline | 28 March 2026 |
| Second review period | 15 March 2026 to 14 March 2027 |
| Filing deadline | 28 March 2027 |
Filing Early Resets the Clock
You can file at any point during the review period, and doing so starts a fresh 12-month period from the date you filed to.
Using the same example: if you filed on 20 March 2026 instead of waiting, your next review period would run to 19 March 2027, with a deadline of 2 April 2027. The dates have moved.
That has two practical consequences. Filing early is a legitimate way to shift an awkward deadline. And if you file an extra statement mid-year to update details, you have changed next year’s date, so do not rely on last year’s diary entry.
The most reliable approach is to check your company’s page on the Companies House register, which shows the next statement date directly, rather than calculating from incorporation.
What the Statement Covers
| Item | Confirmed on the statement |
| Registered office address | Yes |
| Registered email address | Yes |
| Directors and company secretaries | Yes |
| SIC codes (nature of business) | Yes, can be changed on the statement |
| Statement of capital | Yes, can be changed on the statement |
| Shareholder details and share transfers | Yes, can be changed on the statement |
| Trading status of shares | Yes, can be changed on the statement |
| People with significant control | Yes |
| Lawful purpose statement | Yes, a declaration that intended future activities are lawful |
| Director identity verification | Personal codes must be supplied for each director |
The last two are newer additions and both are now mandatory parts of the filing.
What You Must Update Separately Before You File
This is the process detail that causes most rejections, and almost no guidance covers it clearly.
Some information can be changed on the confirmation statement. Other information must be changed first, on a separate form, and the confirmation statement then confirms the updated position.
| Change | How to do it |
| SIC codes | On the confirmation statement |
| Statement of capital | On the confirmation statement |
| Shareholder details and share transfers | On the confirmation statement |
| Appointing a director | Separate form, before filing |
| Removing a director | Separate form, before filing |
| Changing a director’s details | Separate form, before filing |
| Changing the registered office address | Separate form, before filing |
| Changing the registered email address | Separate service, before filing |
| Any change to PSC information | Separate PSC form, before filing |
| Changing where statutory records are kept | Separate form, before filing |
If a director resigned eight months ago and nobody filed the termination, you cannot fix it on the confirmation statement. You file the termination first, then confirm the record. Attempting to do it in one step is the most common reason a statement bounces back.
The sequence is always: check the register, correct what is wrong using the proper forms, then confirm.
How to File: Step by Step
- Check every director has verified their identity: Since 18 November 2025, directors must have verified with Companies House and hold a personal code. The statement will not be accepted without a code for each director. One unverified person blocks the filing for the whole company, so start here rather than discovering it at the end.
- Look up your company on the Companies House register: Read every section as it currently stands: officers, registered office, PSCs, share capital, SIC codes.
- File any separate forms first: Use the table above. Director changes, address changes and PSC changes all need doing before the statement.
- Sign in to file: Most companies use WebFiling with their company authentication code. Accountants and agents typically file through software instead. Paper filing is possible but slower and considerably more expensive.
- Work through the statement. Confirm each section or amend the items that can be changed here, SIC codes, statement of capital, shareholder information.
- Enter the personal codes: One for each director.
- Make a lawful purpose declaration: A confirmation that the company’s intended future activities are lawful.
- Pay and submit: Keep the confirmation receipt and note the next review period end date immediately, because filing early will have moved it.
For a company where nothing has changed and everyone is verified, the whole thing takes a few minutes.
What It Costs
From 1 February 2026 the fee is £50 to file online and £110 by post.
The fee covers a 12-month payment period rather than a single filing, so if you file an additional statement within that period to update details, you do not pay again.
Filing late costs exactly the same as filing on time. There is no surcharge. That is worth knowing if you are already overdue and hesitating, the only thing delay adds is risk.
What Happens If You File Late
The consequences escalate in stages, and each stage is harder to reverse than the last.
Immediately: your company shows as overdue: The status appears on your company’s public page. Banks, lenders, prospective clients and suppliers running a credit check will see it. For a business tendering for work, that is a live commercial problem.
Immediately: the directors are committing an offence: Failure to deliver a confirmation statement is a criminal offence under the Companies Act 2006. Directors can be prosecuted, fined and disqualified.
Typically after a few months: strike-off action begins: Companies House writes to the registered office twice, allowing a reply window on each letter. If there is no response, it publishes a notice in the Gazette under section 1000 of the Companies Act 2006.
Two months after the Gazette notice: dissolution: If nothing is filed and no objection is made, the company is struck off and ceases to exist.
On dissolution: the assets are gone: Under section 1012 of the Companies Act 2006, everything the company owned at the moment of dissolution becomes bona vacantia and passes to the Crown. That means the bank balance, unpaid client invoices, property, domain names, intellectual property and any shares the company held. Banks freeze the account as soon as the dissolution appears on the register.
There is a detail here that costs companies more than any other. Every warning goes to the registered office address. A company using an old accountant’s address, a former trading premises or a service address it stopped paying for will never see any of it. The first the directors hear about it is often when the bank freezes the account.
How to Fix an Overdue Statement
The good news is that the process is designed to be stoppable, and at almost every stage it is.
Before any Gazette notice: File the overdue statement online. It costs the same £50. Filing normally resolves the matter without further consequence.
After a Gazette notice has been published: File the overdue statement, then object to the proposed strike-off through Companies House, stating what you have filed. Do not assume the filing will be picked up automatically in time, make the objection as well. You have two months from the date of the notice.
After dissolution: You are into restoration. Administrative restoration is available for up to six years after dissolution, using form RT01, and requires all outstanding filings to be brought up to date. It costs several hundred pounds in government fees before professional costs, takes weeks, and where the company holds assets a waiver from the Bona Vacantia Division may also be needed. Court restoration is slower and more expensive again.
A restored company is treated as though it had never been dissolved, so contracts revive and assets can be recovered. But the sensible comparison is stark: £50 and ten minutes to file on time, against a restoration process that runs to months and hundreds of pounds.
Mistakes That Cause Rejections and Delays
Assuming the accountant handles it: Confirm explicitly whether your accountant files the confirmation statement or only the accounts. They are entirely separate engagements.
A stale registered office address: Every warning letter, reminder and notice goes there. Keeping it current is the single cheapest piece of protection available.
Trying to change a director on the statement: File the appointment or termination separately first.
Forgetting the review period moved: If you filed early last year, this year’s deadline is not the same date it was.
Overlooking identity verification: A director without a personal code blocks the filing entirely.
Missing the lost authentication code: It goes to the registered office by post and takes days to arrive. Requesting it on the deadline is too late.
Assuming a dormant company is exempt: It is not. Dormancy relieves you of some accounting obligations, not this one.
Treating “no fine” as “no urgency.” The absence of a penalty is the whole trap.
Putting It Into Practice: A Quick Checklist
- Looked up the next statement date on the Companies House register rather than calculating it
- Set a calendar reminder four weeks before that date
- Confirmed the registered office address is current and that post sent there reaches you
- Confirmed every director has verified their identity and holds a personal code
- Checked you have the company authentication code, or requested a replacement in good time
- Reviewed the register entries for officers, PSCs, share capital and SIC codes
- Filed any separate forms needed for director, address or PSC changes before the statement
- Filed the statement and kept the confirmation receipt
- Recorded the new review period end date, which may have moved if you filed early
- Clarified with your accountant exactly which Companies House filings they handle
- If already overdue, filed immediately and objected to any published strike-off notice
Key Takeaways
- The confirmation statement must be filed within 14 days of the end of a 12-month review period, under section 853A of the Companies Act 2006.
- Filing early resets the review period, so next year’s deadline moves.
- The fee is £50 online and £110 by post from 1 February 2026, covering a 12-month payment period regardless of how many statements you file in it.
- There is no automatic late filing penalty, which is precisely why directors leave it and why it ends in strike-off.
- Director changes, registered office changes and PSC changes must be filed on separate forms before the statement, not on it.
- Every director must have verified their identity and supplied a personal code before the statement can be filed.
- On dissolution, company assets become bona vacantia under section 1012 and pass to the Crown, with bank accounts frozen immediately.
Frequently Asked Questions
When is my confirmation statement due?
Within 14 days of the end of your 12-month review period. The first review period starts on your incorporation date; each one after that begins the day after the previous period ended. The next statement date is shown directly on your company’s page on the Companies House register.
What is the penalty for a late confirmation statement?
There is no automatic financial penalty, unlike late accounts. However, failing to file is a criminal offence for the directors, the overdue status is publicly visible, and persistent failure leads to the company being struck off and dissolved.
Do I need to file if nothing has changed?
Yes. The purpose of the statement is to confirm the record is accurate, and confirming that nothing has changed is still a filing you must make. This applies equally to dormant and non-trading companies.
How much does it cost to file a confirmation statement?
£50 online and £110 by post from 1 February 2026. The fee covers a 12-month payment period, so additional statements filed within that window are free. Filing late costs the same as filing on time.
Can I change the director on the confirmation statement?
No. Director appointments, terminations and detail changes must be filed on separate forms before you submit the statement. The same applies to the registered office address and PSC information. SIC codes, share capital and shareholder details can be changed on the statement itself.
My company was struck off. Can I get it back?
Administrative restoration is available for up to six years after dissolution using form RT01, provided all outstanding filings are brought up to date. It costs several hundred pounds in government fees plus professional costs, and where the company holds assets a waiver from the Bona Vacantia Division may be required. Court restoration is the alternative and is more expensive.
I have had a Gazette strike-off notice. What should I do?
File the overdue statement immediately, then separately object to the proposed strike-off through Companies House, explaining what you have filed. You have two months from the date of the notice. Do not rely on the filing being noticed in time on its own.
Conclusion
The confirmation statement is a ten-minute job that costs £50, and it ends more companies than any other filing on the calendar. Not because it is difficult, but because nothing arrives to make you do it. There is no penalty notice, no demand, no escalating figure. Just an overdue marker on a public page that nobody in the company is looking at, and warning letters going to an address the company may have left years ago.
The two habits that prevent all of it are trivial. Keep the registered office address somewhere you actually receive a post. Take the next statement date from the register itself the moment you file, rather than assuming it is the same as last year.
At Aksons Accounting we track confirmation statement dates alongside accounts and Corporation Tax deadlines for every company we look after, and file them as part of the monthly service. If yours is already showing as overdue, or you are not certain who is responsible for filing it, send us your company number and we will check the position and tell you what needs doing.